Foreign selling, thinner turnover deepen DSE correction as capital rotates into bonds
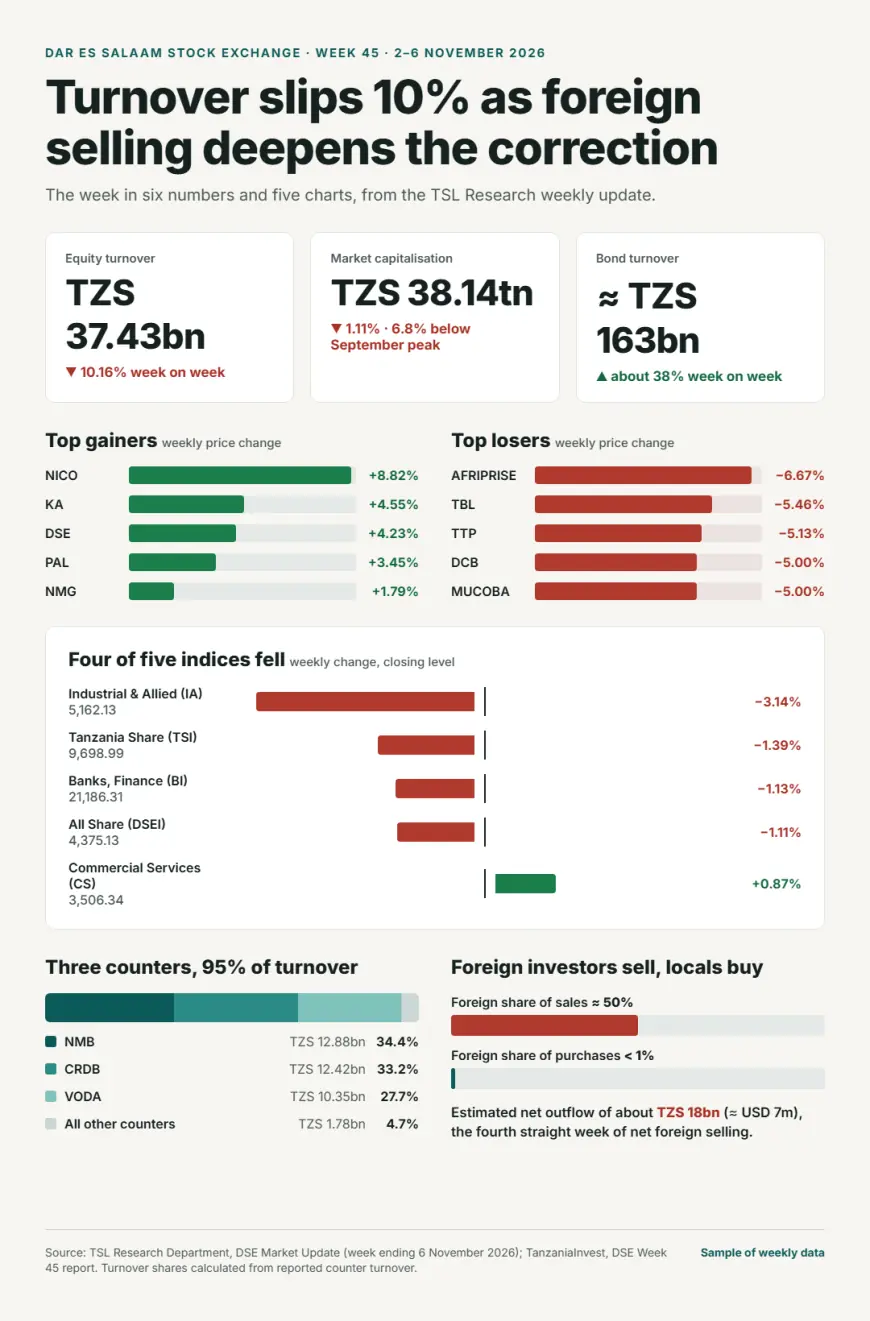
The Dar es Salaam Stock Exchange (DSE) extended its correction in the week to November 6, 2026 with equity turnover falling 10.16 percent to Sh37.43 billion and foreign investors selling heavily for a fourth consecutive week.
Total market capitalisation slipped 1.11 percent to Sh38.14 trillion, leaving it about 6.8 percent below its September peak of Sh40.9 trillion.
A late-week rally in NICO, which rose 8.82 percent, was not enough to offset losses among banks and industrials, while the bond market recorded a 38 percent jump in turnover as yields on longer maturities eased.
Banks and industrials weigh on the indices
Four of the five DSE indices closed lower. The All Share Index (DSEI) lost 1.11 percent to 4,375.13 and has now fallen for four consecutive weeks.
The Tanzania Share Index (TSI) shed 1.39 percent to 9,698.99, remaining below the 10,000 mark throughout the week, while the Banks, Finance & Investment index (BI) eased 1.13 percent to 21,186.31.
The sharpest decline came in the Industrial & Allied index (IA), which dropped 3.14 percent to 5,162.13 after Tanzania Breweries (TBL) slipped below the Sh10,000 level, closing at Sh9,700, a weekly fall of 5.46 percent.
Commercial Services (CS) was the only index to advance, rising 0.87 percent to 3,506.34.
At stock level, NICO led the gainers, climbing from Sh3,400 to Sh3,700 on a strong late-week rally.
KA added 4.55 percent to Sh115, DSE rose 4.23 percent to Sh6,400, PAL gained 3.45 percent to Sh300 and NMG edged up 1.79 percent to Sh285.
On the losing side, AFRIPRISE fell 6.67 percent to Sh700, followed by TBL, TTP (down 5.13 percent to Sh370), DCB and MUCOBA (each down 5.00 percent to Sh380).
KCB, MCB, MKCB, NMB and TOL have each now lost ground for at least three consecutive weeks, pointing to sustained selling pressure in those counters.
Trading narrows to 3 counters as foreigners sell
Activity remained heavily concentrated.
NMB (Sh12.88 billion), CRDB (Sh12.42 billion) and Vodacom Tanzania (VODA, Sh10.35 billion) together generated about 95 percent of the week's equity turnover.
VODA led by volume with 8.28 million shares, out of 19.82 million shares traded across 14,840 deals, a 7.00 percent increase in shares changing hands.
The mix shifted sharply from the previous week. NMB's turnover fell 39.57 percent from Sh21.30 billion, while CRDB's rose 31.99 percent from Sh9.41 billion and VODA's climbed 265.57 percent from Sh2.83 billion.
Turnover in TCC and TBL, which had been among the heavier traders a week earlier, collapsed by 88.65 percent and 85.85 percent to Sh515.80 million and Sh380.42 million respectively.
Foreign investors were heavy net sellers.
They accounted for roughly half of all sales by value but less than 1 percent of purchases, while local investors absorbed more than 99 percent of buying interest.
The imbalance equates to an estimated net outflow of about Sh18 billion, or roughly $7 million, and extends a streak of foreign net selling to four weeks.
Exchange-traded funds also cooled.
Combined ETF turnover fell 63.08 percent to Sh842.20 million, with IEACLC-ETF down 2.16 percent to Sh1,360 and VERTEX-ETF down 3.17 percent to Sh305, while ZAN TIMIZA ETF was unchanged at Sh120.
Bonds draw capital as long-dated yields ease
While equities cooled, the bond market strengthened.
Weekly turnover rose by about 38 percent to roughly Sh163 billion from Sh118 billion, across 223 deals, supported by what TSL Research described as a record Sh72.08 billion session on 3 November.
Trading was concentrated at the long end.
The 25-year tenor accounted for 67.32 percent of turnover, followed by the 20-year at 23.95 percent and the 5-year at 5.60 percent, with I&M and ABK corporate bonds making up the remainder.
TSL's daily data point to firm demand and falling yields.
The 20-year yield declined 153 basis points over the week to 10.74 percent from 12.27 percent, with its price rising to 117.10 from 110.21.
The 15-year yield fell 73 basis points to 10.47 percent, and the 25-year closed at 10.62 percent after swinging between 10.13 and 10.84 percent.
In the corporate segment, the SAMIA bond's yield eased to 13.08 percent from 15.23 percent.
The picture is less uniform on a weighted-average basis.
TanzaniaInvest's compilation shows the 25-year yield easing 31 basis points to 10.44 percent and the 20-year 17.6 basis points to 10.76 percent, but the 5-year yield rising 54 basis points to 11.32 percent, a flattening of the curve.
The two measures use different methods, and readings at the shorter end of the curve conflict, so the direction of yields beyond the long end should be treated with caution.
Foreign flows and the 10,000 level in focus
Despite the pullback, total market capitalisation remains roughly 59 percent above its January level of about Sh24 trillion, and several large counters retain strong year-to-date gains, among them NICO (up 98.20 percent), VODA (87.19 percent) and CRDB (86.31 percent).
Income-focused investors may also take note of dividend yields of 7.49 percent at TCC, 5.45 percent at TBL and 5.21 percent at TPCC, the highest among listed counters.
In the coming week, attention is likely to centre on whether foreign selling abates after four weeks of net outflows, whether the TSI can reclaim the 10,000 mark, and whether bond demand holds at the next government auction, a 10-year Treasury bond scheduled for 11 November.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0